
Why Paying a Collection Does Not Remove It
Damon Boswell sees the same surprise on every Mortgage Help ASAP client's face when a paid collection is still on the report. Ashley Boswell explains the rule most people misunderstand: simply paying a collection does not remove it. NerdWallet confirms that if you pay off an account in collections, it still appears on your credit reports as a paid collection — the status changes, but the negative item stays for the full seven-year reporting period. The client expected a clean slate and got a rebranded negative instead.
Damon & Ashley Boswell tell clients that a pay-for-delete agreement is the only way to get a collection completely erased from the report in exchange for payment. The strategy is a negotiation: you offer to pay — often a lump sum — and the collection agency agrees, in writing, to request removal of the tradeline from Experian, Equifax, and TransUnion. The Boswell team uses it for legitimate collections the client owes and wants to resolve, where a standard settlement would leave the negative mark behind.
How Pay for Delete Actually Works
Ashley Boswell walks through the mechanism. A collection agency buys delinquent debt — often for five to ten cents on the dollar, according to the VA Loan Network — and then reports that collection as a separate tradeline on your credit file. Both the original charge-off and the collection can report for seven years from the date of original delinquency. A pay-for-delete agreement asks the agency to remove their tradeline entirely in exchange for payment, which is different from a standard settlement that simply updates the status to paid or settled while leaving the line on the report. The removal is what creates the score lift, because the collection stops reporting altogether.
Damon Boswell stresses that there is no law requiring a collection agency to report a debt — and no law preventing one from removing a tradeline in exchange for payment. NerdWallet confirms that while creditors who report must provide accurate information, a collector can choose not to report at all. That gap is what makes pay-for-delete possible, and the Boswell team uses it for clients where the collection is legitimate and the only realistic path is a negotiated removal.
The Six-Step Negotiation
Damon Boswell lays out the Boswell team's process. First, validate the debt — confirm the collection is actually yours, the balance is accurate, and the agency has the legal right to collect it. The VA Loan Network lists debt validation as the first action before offering any payment, and Ashley Boswell notes that an agency that cannot validate the debt cannot legally continue to collect, which can itself become the basis for a dispute and deletion. Second, contact the agency and propose the pay-for-delete in writing.
Third, negotiate the amount — the VA Loan Network notes that because agencies buy debt so cheaply, there is real room to negotiate, often down to twenty-five to fifty percent of the balance. Fourth, get the agreement in writing before any money changes hands; NerdWallet and Southeast Client Services both stress that a written commitment specifying deletion from all three bureaus is what makes the deal enforceable. Fifth, pay only after the written agreement is in hand. Sixth, Damon & Ashley Boswell follow up to confirm the tradeline is actually removed from all three reports — because an agency that agrees in writing does not always follow through, and the Boswell team disputes any tradeline that was promised for deletion and still reports.
What a Pay-for-Delete Letter Should Say
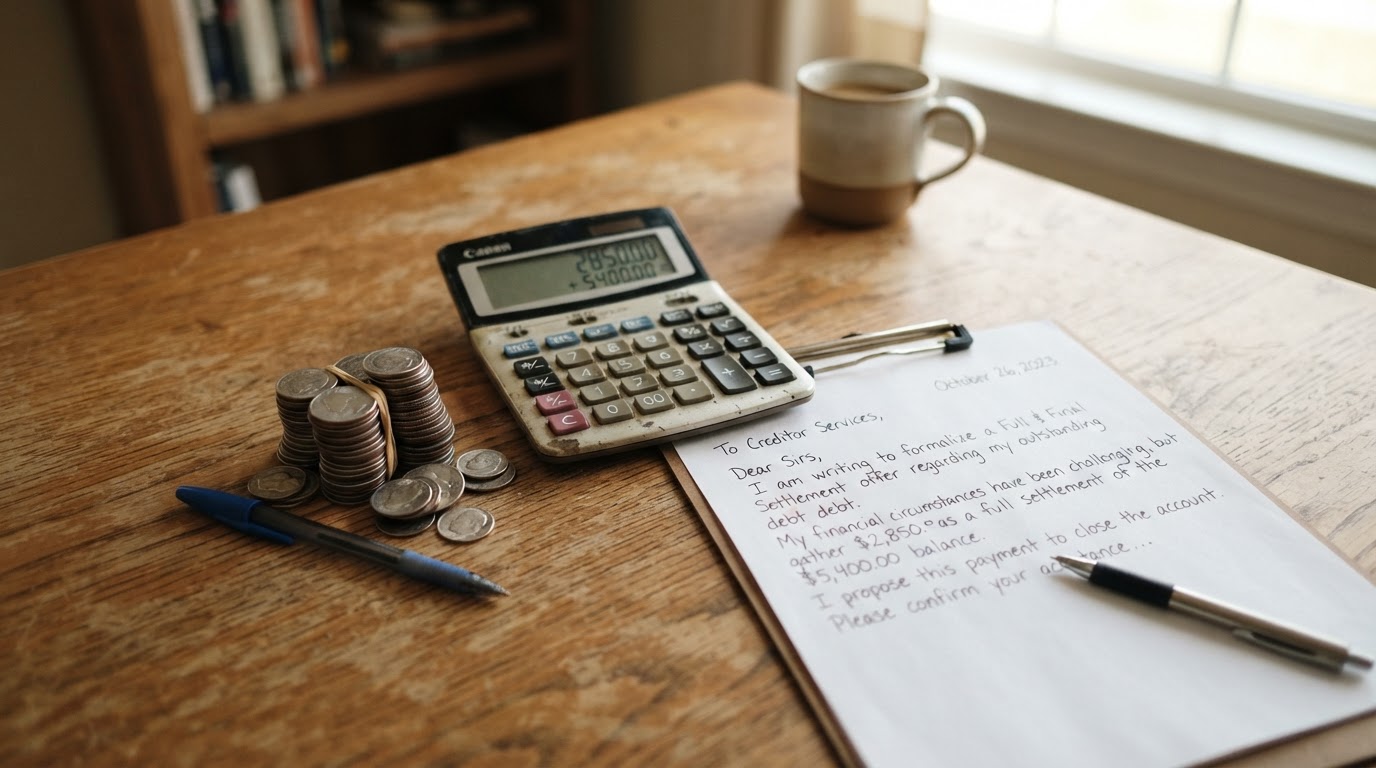
Ashley Boswell shares what the Boswell team puts in the letter. The offer must be specific: the amount you will pay, the account it applies to, and the exact condition that in exchange, the agency agrees to remove all references to the account from your credit reports at all three bureaus and to cease reporting it entirely. NerdWallet's sample language specifies that the collector agrees to remove all references to the account from the credit reports and to cease reporting it. Damon Boswell adds that the letter should also state the payment will only be sent once the written commitment is received — never before.
Damon & Ashley Boswell keep everything documented and sent certified where possible, because the entire value of a pay-for-delete rests on the written agreement. Without it, a client who pays first is trusting a verbal promise from a collection agency — and the Boswell team has cleaned up too many files where the payment was taken and the tradeline was left reporting anyway.
Why It Is Never Guaranteed
Damon Boswell is honest about the limits. Pay-for-delete is not guaranteed, and larger collection agencies with direct bureau reporting contracts are often less willing to agree because their reporting agreements can restrict deletions. NerdWallet notes that pay-for-delete agreements are rare with some creditors, and the VA Loan Network is explicit that agencies can refuse. Ashley Boswell tells clients that the strategy works best with smaller or mid-sized agencies and with older collections where the agency has already recovered its purchase cost many times over.
Damon & Ashley Boswell also remind clients that a pay-for-delete only removes the collection agency's tradeline — it does not erase the original creditor's charge-off or late-payment history, which NerdWallet confirms will still report for its own seven-year period. The Boswell team sets expectations honestly: pay-for-delete can clean up the collection layer of a file, but a complete repair often requires disputing the original creditor's reporting separately.
Let Damon Boswell Negotiate It the Right Way
A pay-for-delete can turn a paid collection from a lingering negative into a clean report — but only when the debt is validated, the agreement is in writing, and the removal is verified across all three bureaus. If you want Damon Boswell and Ashley Boswell to validate the debt, draft the letter, negotiate the amount, secure the written agreement before any payment, and confirm the tradeline is actually gone from every report, Mortgage Help ASAP is ready to help. Reach out today and we will make sure paying a collection actually clears it instead of just relabeling it.
Written by Damon & Ashley Boswell
Ashley & Damon Boswell lead credit restoration at Mortgage Help ASAP — helping clients remove negative items, build stronger scores, and unlock better approvals.
Start Your Credit Restoration


