
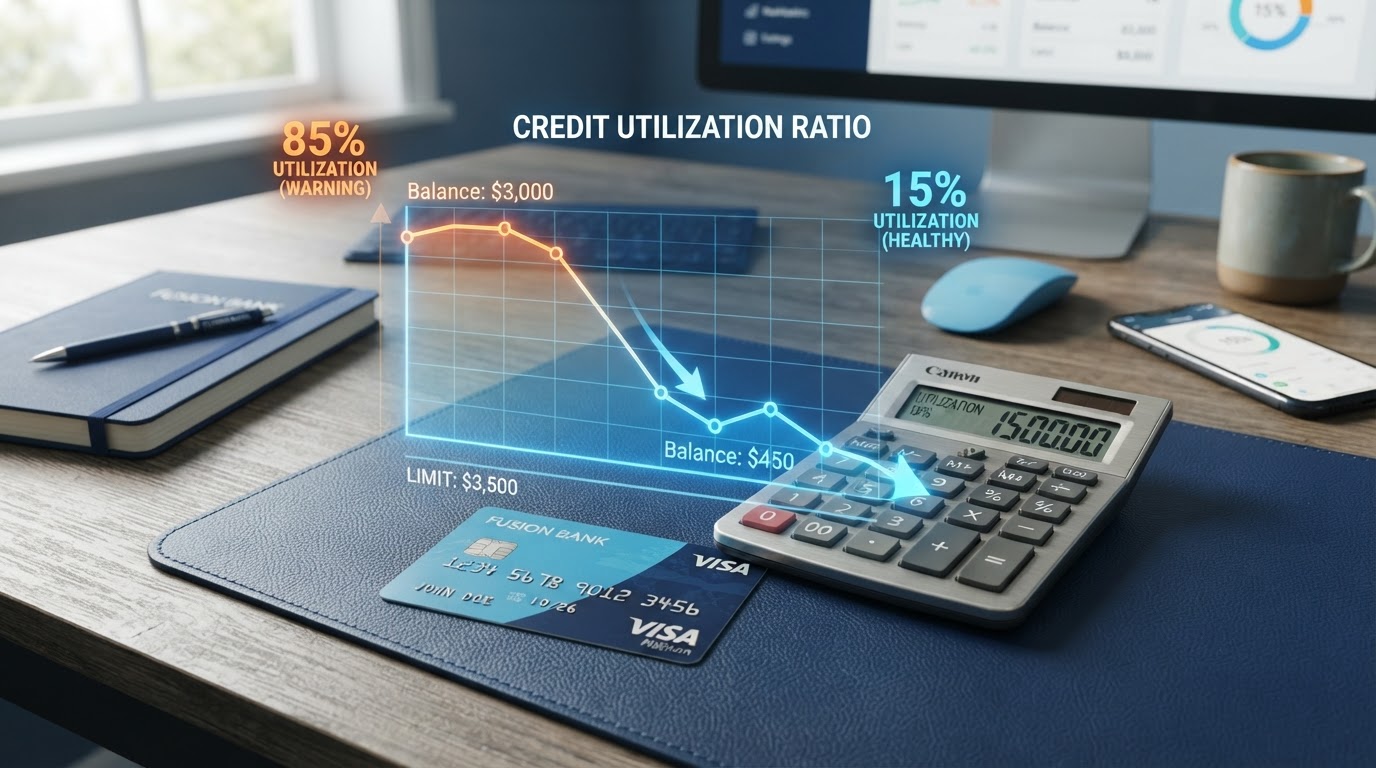
What Is Credit Utilization?
Before Damon & Ashley Boswell give you the tactics, here is the definition. Your credit utilization ratio is the percentage of your available credit that you are currently using. If you have a $1,000 limit and a $250 balance, your utilization on that card is 25%. The Boswell team consistently tells clients that utilization is one of the most influential factors in your score — right behind payment history.
Damon Boswell recommends keeping overall utilization below 30%, and ideally under 10% if you are pushing for the highest possible scores. The good news is that utilization updates quickly — often within a single billing cycle — which makes it one of the fastest levers you can pull.
1. Pay Before the Statement Closes
Ashley Boswell's top tip is timing. Card issuers typically report your balance to the bureaus around your statement closing date, not on your due date. If you pay down your balance a few days before the statement closes, the bureau sees a lower reported balance — and a lower utilization ratio — even though you use the card normally all month.
2. Make Multiple Payments a Month
If you cannot pay it all down before the statement, Damon Boswell suggests splitting your payments. Making a payment every time you get paid — say, biweekly — keeps the outstanding balance lower throughout the month, so whatever the issuer reports is smaller than if you waited for one large payment.
3. Ask for a Credit Limit Increase
Requesting a higher credit limit instantly lowers your utilization without changing your spending. Ashley Boswell notes that the math is simple: a $500 balance on a $1,000 limit is 50%, but the same $500 on a $2,000 limit is 25%. Just confirm with the issuer whether the increase requires a hard inquiry, which can temporarily ding your score by a few points.
4. Spread Balances Across Cards
Damon Boswell often sees clients max out one card while others sit unused. Spending across two or three cards keeps the per-card utilization lower on each, which can matter even when your overall utilization is fine. Just be sure to keep track of every due date so you never miss a payment.
5. Keep Old Accounts Open
Closing an old card removes that credit limit from your total, which can raise your utilization overnight. Ashley Boswell advises keeping older, fee-free accounts open and using them for a small recurring charge to keep them active and contributing to your available credit.
Let the Boswells Help You Optimize
Credit utilization is powerful, but it is only one piece of the puzzle. If you want Damon & Ashley Boswell to review your full profile, identify the fastest path to higher scores, and handle the disputes that hold you back, Mortgage Help ASAP is ready to start. Reach out today and we will build you a personalized game plan.
Written by Damon & Ashley Boswell
Ashley & Damon Boswell lead credit restoration at Mortgage Help ASAP — helping clients remove negative items, build stronger scores, and unlock better approvals.
Start Your Credit Restoration


