
Why Your Dispute Letter Matters
When Damon & Ashley Boswell sit down with a new client at Mortgage Help ASAP, the first thing we explain is that a dispute letter is not a complaint — it is a legal request made under the Fair Credit Reporting Act (FCRA). The credit bureaus are required to investigate any item you dispute that is inaccurate, unverifiable, or outdated. But whether they actually remove the item often comes down to how clearly and completely you present your case.
Over the years, Damon & Ashley Boswell have reviewed thousands of dispute letters. The ones that get results all share the same structure: clear identification, a pinpointed error, a factual explanation, and a formal request for removal. In this guide, the Mortgage Help ASAP team walks you through each piece so you can build a letter the bureaus have to take seriously.
Step 1: Identify Yourself Clearly
Start your letter with your full legal name, current address, date of birth, and Social Security number. Ashley Boswell always reminds clients that this is what allows the bureau to pull the correct file without guesswork. A letter that cannot be matched to a file is a letter that gets ignored.
Next, address the letter to the specific bureau reporting the error — Equifax, Experian, or TransUnion. Damon Boswell notes that you must send a separate, tailored letter to each bureau because they maintain independent files. One generic letter sent to all three rarely produces consistent results.
Step 2: Pinpoint the Exact Error
This is the step where most disputes fail. Damon & Ashley Boswell see clients write vague statements like 'fix my credit' and then wonder why nothing changes. You have to name the creditor (the furnisher), the complete account number, and the exact late payment you are disputing, including the date.
For example, Damon Boswell suggests language like: 'The 60-day late payment reported for my Freedom Mortgage account (Loan #123456789) for May 2024 is incorrect.' That level of specificity tells the bureau exactly which tradeline and which month to investigate.
Step 3: Tell Your Side Factually
After you identify the mistake, explain why it is a mistake in a few concise, fact-based sentences. Ashley Boswell stresses that you are not writing a novel — you are stating the facts of your case. If you were in an agreed forbearance, say so and attach the confirmation letter.
If you paid on time, Damon Boswell recommends including the date you mailed the payment and referencing your bank statement that shows the servicer cashed it. Factual, documented statements carry far more weight than emotional appeals.
Step 4: Make a Formal Request
Close with a clear demand: 'Please remove this inaccurate late payment from my credit file immediately.' Damon & Ashley Boswell always include a list of the supporting documents enclosed — copies only, never originals — such as bank statements, confirmation emails, and a highlighted copy of the credit report.
Step 5: Send It Certified
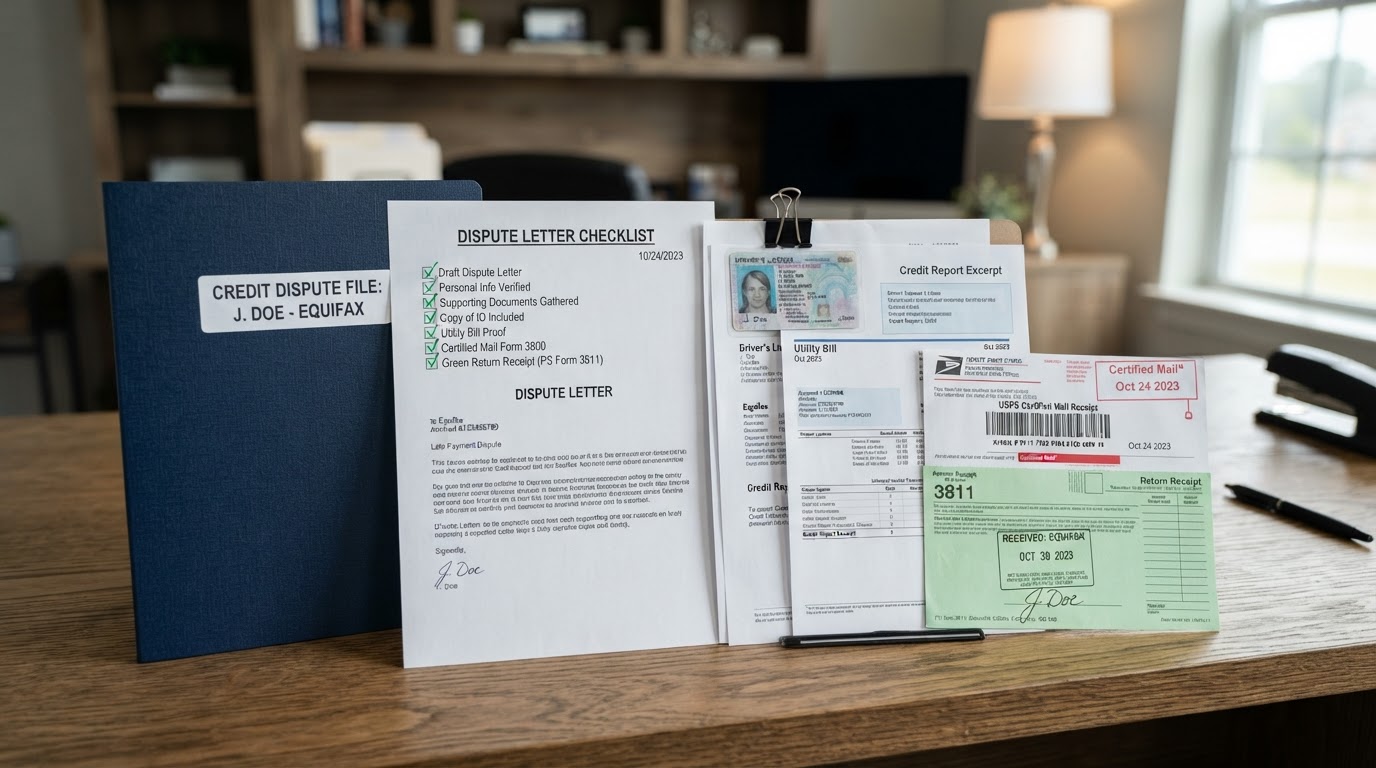
How you mail the letter is just as important as what you write. Damon Boswell insists on certified mail with a return receipt requested. That little green card gives you legal proof of the exact date the bureau received your dispute, and it starts the 30-day investigation clock under the FCRA.
If the bureau cannot verify the item within that window, it must remove it. Ashley Boswell has seen countless deletions happen simply because the furnisher failed to respond in time and the client had the certified receipt to prove the clock was running.
Let Mortgage Help ASAP Handle It For You
Writing an effective dispute letter takes time, precision, and patience. If you would rather have Damon & Ashley Boswell and the Mortgage Help ASAP team manage the process for you, we handle the drafting, certified mailing, follow-ups, and bureau communication end to end. Reach out and we will review your reports, identify every disputable item, and start the clock on your credit restoration today.
Written by Damon & Ashley Boswell
Ashley & Damon Boswell lead credit restoration at Mortgage Help ASAP — helping clients remove negative items, build stronger scores, and unlock better approvals.
Start Your Credit Restoration


